Debt Payoff Strategies
The debt strategy that saves the most interest isn't always the one people actually finish, and research backs that up.
By Greg Goodwin · Published September 10, 2026 · Updated October 24, 2026
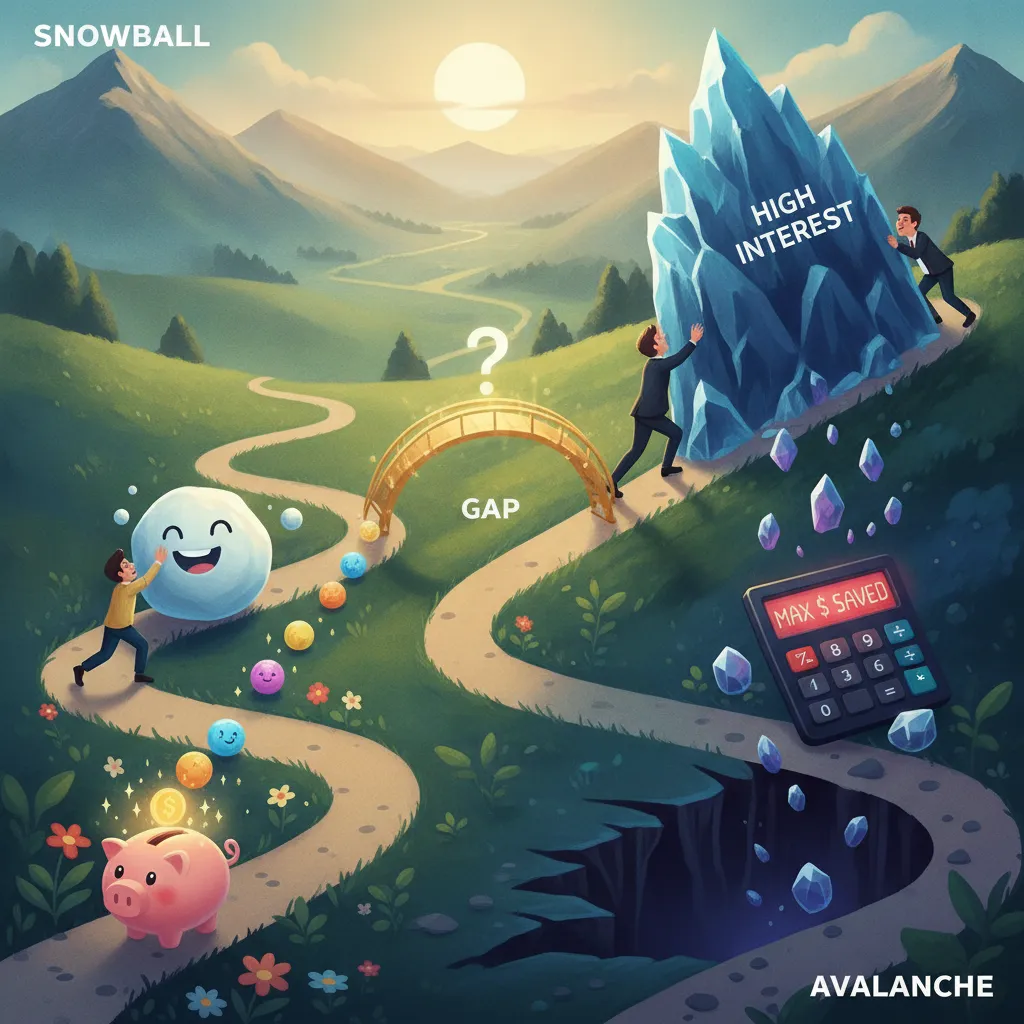
Cheat Sheet
- The 'debt avalanche' method pays off debts in order of highest interest rate first, minimizing total interest paid over time.
- The 'debt snowball' method pays off debts in order of smallest balance first, prioritizing psychological momentum over pure math.
- Research on the snowball method (notably a 2016 Harvard Business Review-cited study) found early small wins can meaningfully improve follow-through, despite costing more in total interest.
- Debt consolidation combines multiple debts into a single loan, often at a lower interest rate, simplifying payments into one monthly bill.
- Making only minimum payments on high-interest debt like credit cards can take years or decades to pay off, due to how interest compounds on the remaining balance.
- Both major payoff strategies require making at least minimum payments on all debts, with any extra money directed toward the prioritized target debt.
The 60-Second Version
Two competing strategies dominate most discussions of paying down multiple debts, and they optimize for genuinely different things. The debt avalanche method targets whichever debt carries the highest interest rate first, which is the mathematically optimal approach for minimizing the total interest paid over the life of all the debts combined. The debt snowball method instead targets the smallest balance first, regardless of interest rate, prioritizing quick psychological wins and momentum over pure mathematical efficiency. Research examining actual follow-through, rather than theoretical optimal outcomes, has found that the snowball method's early small victories can meaningfully improve whether people actually stick with a payoff plan long enough to finish it, even though it typically costs more in total interest paid along the way. For people juggling several different debts, consolidation offers a third path entirely, combining multiple balances into a single new loan, often at a more favorable interest rate, which simplifies the whole situation down into one predictable monthly payment. Whichever specific method someone chooses, both require continuing to make at least the minimum payment on every other debt, directing any extra available money specifically toward the one prioritized target debt at a time.
The Long Version
The Mathematically Optimal Approach
The debt avalanche method targets whichever remaining debt carries the highest interest rate first, directing any extra available payment toward that specific balance while maintaining minimum payments on everything else, an approach that's mathematically optimal for minimizing the total amount of interest paid across all debts combined by the time everything's paid off.
The Psychologically Motivating Alternative
The debt snowball method instead targets the smallest remaining balance first, regardless of what interest rate it actually carries, deliberately trading some mathematical efficiency for the psychological benefit of eliminating an entire debt relatively quickly, generating an early sense of visible progress and momentum.
What the Research Actually Shows
Research examining real-world follow-through, rather than purely theoretical optimal outcomes, has found that the snowball method's early small wins can meaningfully improve whether people actually stick with a debt payoff plan all the way through to completion, even though the approach typically costs more in total interest paid over the full payoff timeline compared to the mathematically optimal avalanche method.
A Third Option, and the Shared Ground Rules
For people juggling several different debts at once, consolidation offers a genuinely different path, combining multiple existing balances into a single new loan, often at a more favorable interest rate, which simplifies an otherwise complicated situation down into one predictable monthly payment rather than several separate ones. Whichever specific strategy someone ultimately chooses, all of them require continuing to make at least the minimum required payment on every other debt, while directing any extra available money specifically toward the one currently prioritized target debt.
Why People Care
Choosing the right debt payoff strategy can make a real difference in both how much interest someone ultimately pays and whether they actually follow through to becoming debt-free, and understanding the genuine trade-off between mathematical efficiency and psychological motivation helps people pick the approach they're actually likely to stick with.
Glossary
- Debt avalanche
- A debt payoff strategy targeting the highest-interest-rate debt first, minimizing total interest paid over time.
- Debt snowball
- A debt payoff strategy targeting the smallest balance first, prioritizing psychological momentum and early wins.
- Debt consolidation
- Combining multiple debts into a single loan, often at a lower interest rate, to simplify payments into one monthly bill.
- Minimum payment
- The smallest amount a borrower must pay each period to keep a debt in good standing, generally covering little more than accrued interest.
- Compound interest (on debt)
- Interest calculated on both the original balance and previously accrued interest, which can cause debt to grow quickly if only minimum payments are made.
Go Deeper
More to Explore
- Mortgages
A mortgage is how ordinary people buy something worth many years of salary: by promising to pay for it slowly, with interest.
- Emergency Funds
A Federal Reserve survey once found that roughly a third of American adults would struggle to cover a surprise $400 expense using cash on hand.
- Income Taxes
Landing in a higher tax bracket doesn't tax all your income at the higher rate, only the slice that falls inside that bracket.
- Retirement Accounts
Compound growth is why starting retirement savings early beats saving more later: time does the heavy lifting.
- Insurance Basics
Insurance is risk pooling: many people pay premiums so the few hit by rare, severe losses can afford to recover.